
Citrus Pulp CAS: 94266-47-4
Citrus Pulp CAS: 94266-47-4
Chinese amino acid producers (L-lysine, L-threonine, taurine, L-methionine, choline chloride) serve global nutraceutical
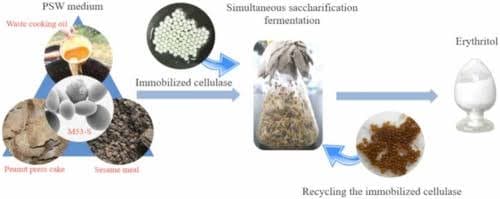
Chinese erythritol producers expanded fermentation capacity through H1 2026 just as GLP-1 driven demand for sugar-free products began accelerating globally. For food and beverage manufacturers, July may be the strongest opportunity to lock competitive H2 erythritol supply before structural demand growth tightens the market later this year.
The upcoming VCI Q2 2026 report underscores a sharp decline in German chemical production, driven by soaring feedstock costs and weak domestic demand. Naphtha‑based downstream plants are hit hardest, while export disruptions to Asia and the Gulf further strain utilization rates. For buyers, the data offers critical insight into supplier stability and pricing dynamics across Europe.
Hospital pharmacies are entering H2 2026 with improving supply conditions after months of inventory pressure. Q3 is expected to become the largest pharmaceutical chemical restocking period since before the Hormuz crisis.
Freight conditions are changing rapidly for global citric acid buyers as shipping routes recover and logistics costs begin to ease. Procurement teams negotiating H2 2026 contracts have a short opportunity to secure improved delivered pricing before freight adjustments spread across the market.
Saudi Arabia’s Ras Tanura restart is improving confidence in Gulf chemical logistics and methanol availability. This analysis explains how recovering supply, crude prices and shipping conditions could influence Q3 methanol procurement strategies.
Estamos comprometidos com sua privacidade. A Tradeasia usa as informações fornecidas para entrar em contato com você sobre conteúdos, produtos e serviços relevantes. Para mais informações, consulte nossa política de privacidade.