
Cetyl Palmitate CAS: 0540-10-3
Cetyl Palmitate CAS: 0540-10-3
China’s ongoing ban on phosphate exports pushes global fertilizer markets into uncertainty, tightening DAP and MAP supplies, reshaping shipping routes, and forcing buyers to rethink procurement strategies. The ripple effect underscores the fragility of the agricultural input supply chain.
The European Union’s new customs duties on Russian nitrogen, phosphate, and potash have forced farmers and traders worldwide to rethink sourcing, logistics, and pricing strategies. This article explores how the tariffs are reshaping global fertilizer markets, freight routes, and procurement decisions across the agricultural supply chain.
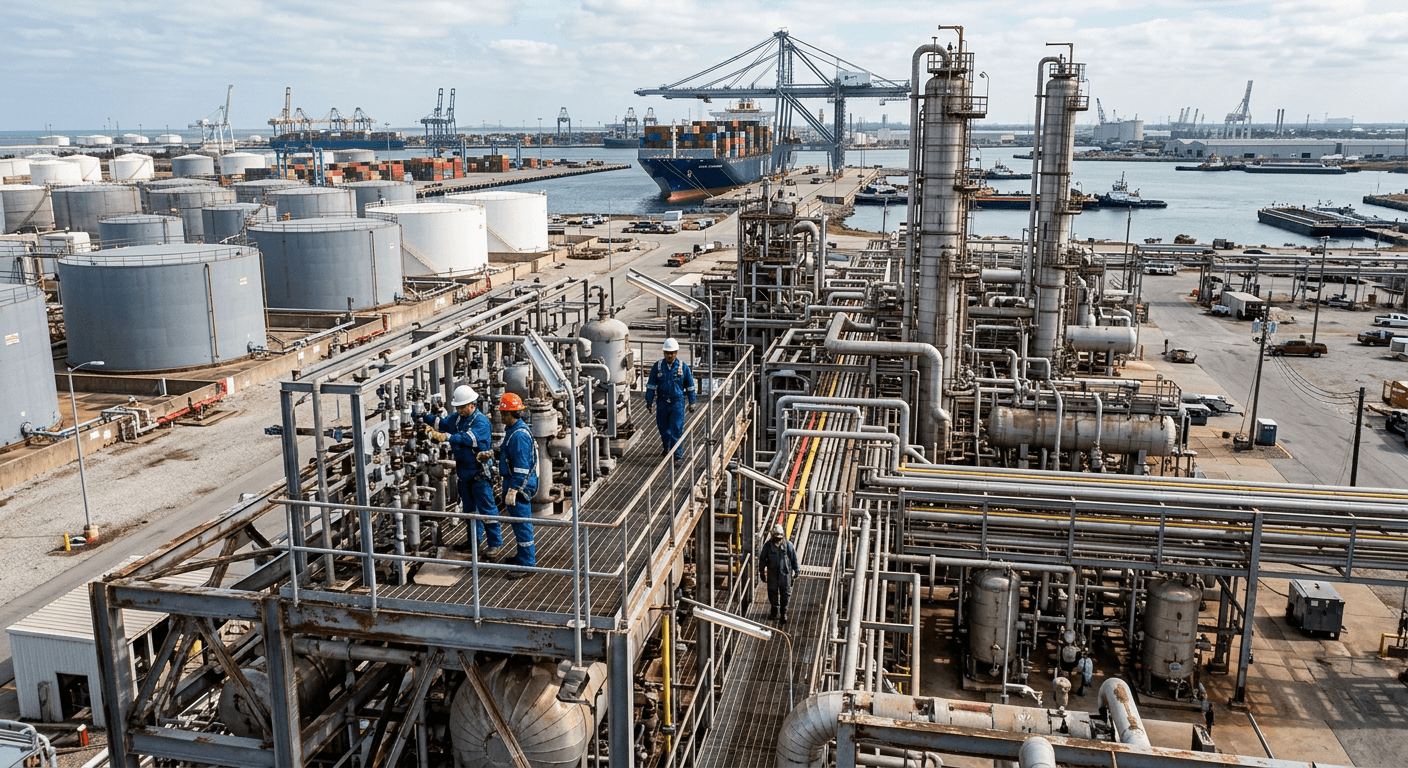
Doha Talks Today has become a key market signal for chemical buyers watching Gulf trade routes, energy flows and supply stability. This venue shift may influence procurement decisions as traders assess risks across major chemical exporting regions.
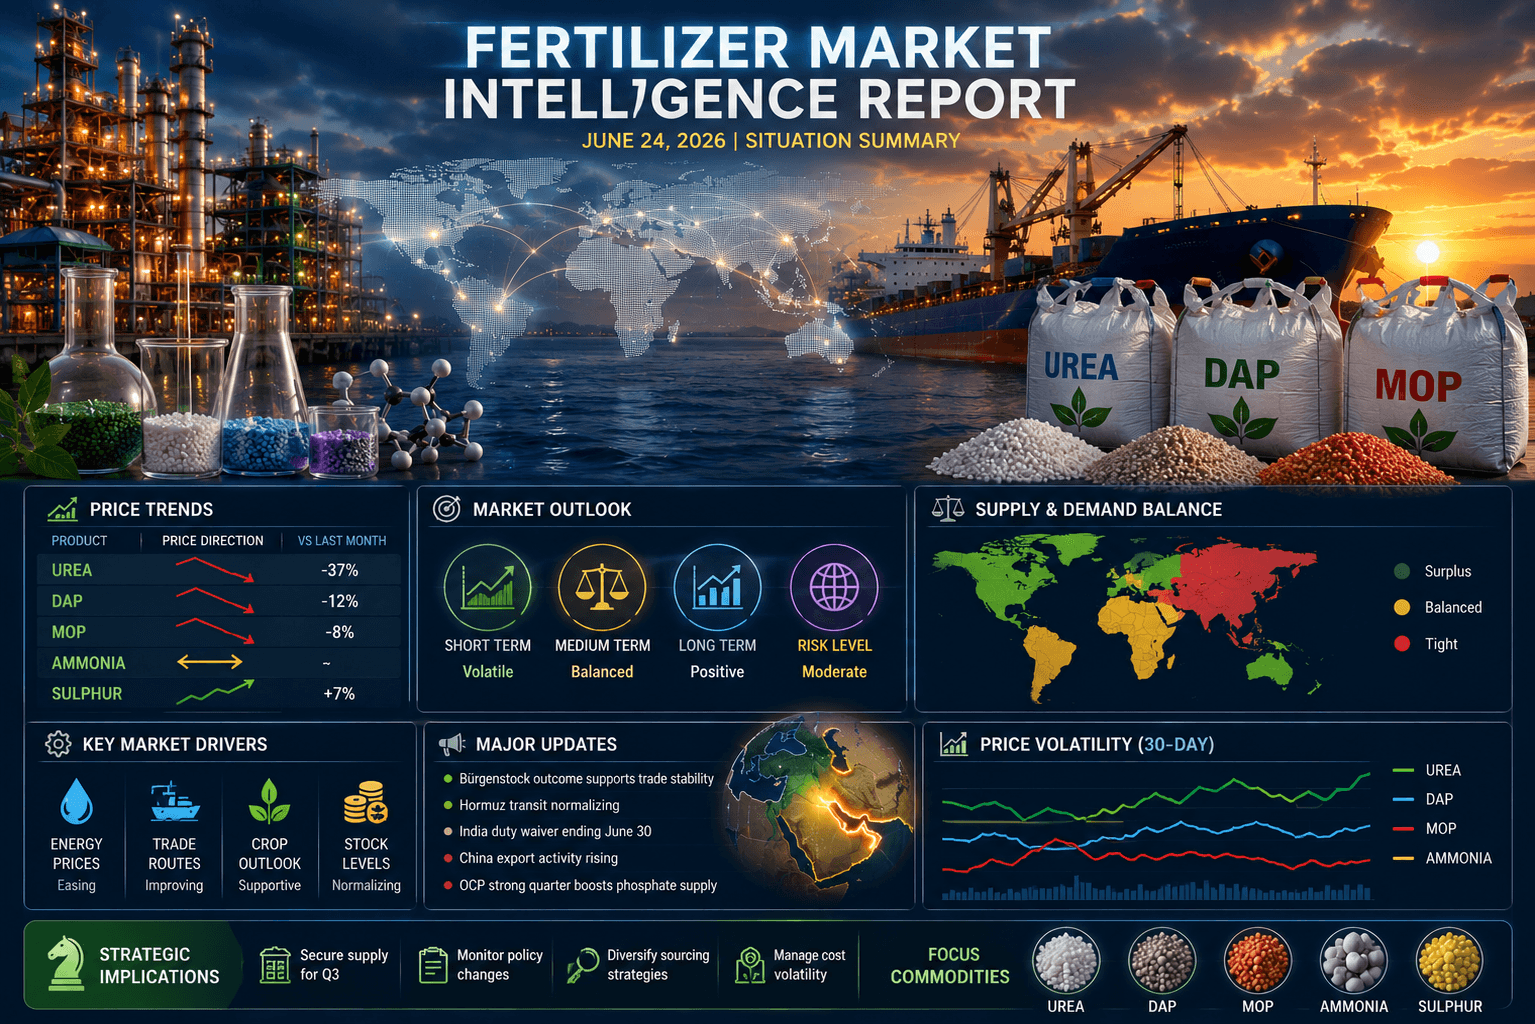
Global fertilizer markets are stabilizing after months of disruption, but June 2026 remains a critical procurement window. Urea prices are down 36%, ammonia exports may restart in July, and fertilizer buyers must navigate supply recovery, policy deadlines, and pricing uncertainty.
Hengli Petrochemical reported a remarkable 90.65% year-on-year increase in net profit during Q1 2026 as supply disruptions around the Strait of Hormuz altered global trade flows. This article examines the factors behind China's refining advantage, the export surge that followed and what buyers should expect as Middle Eastern supply returns to the market.
Estamos comprometidos com sua privacidade. A Tradeasia usa as informações fornecidas para entrar em contato com você sobre conteúdos, produtos e serviços relevantes. Para mais informações, consulte nossa política de privacidade.