
Diammonium Phosphate (Technical 18-46) - Morocco CAS: 7783-28-0
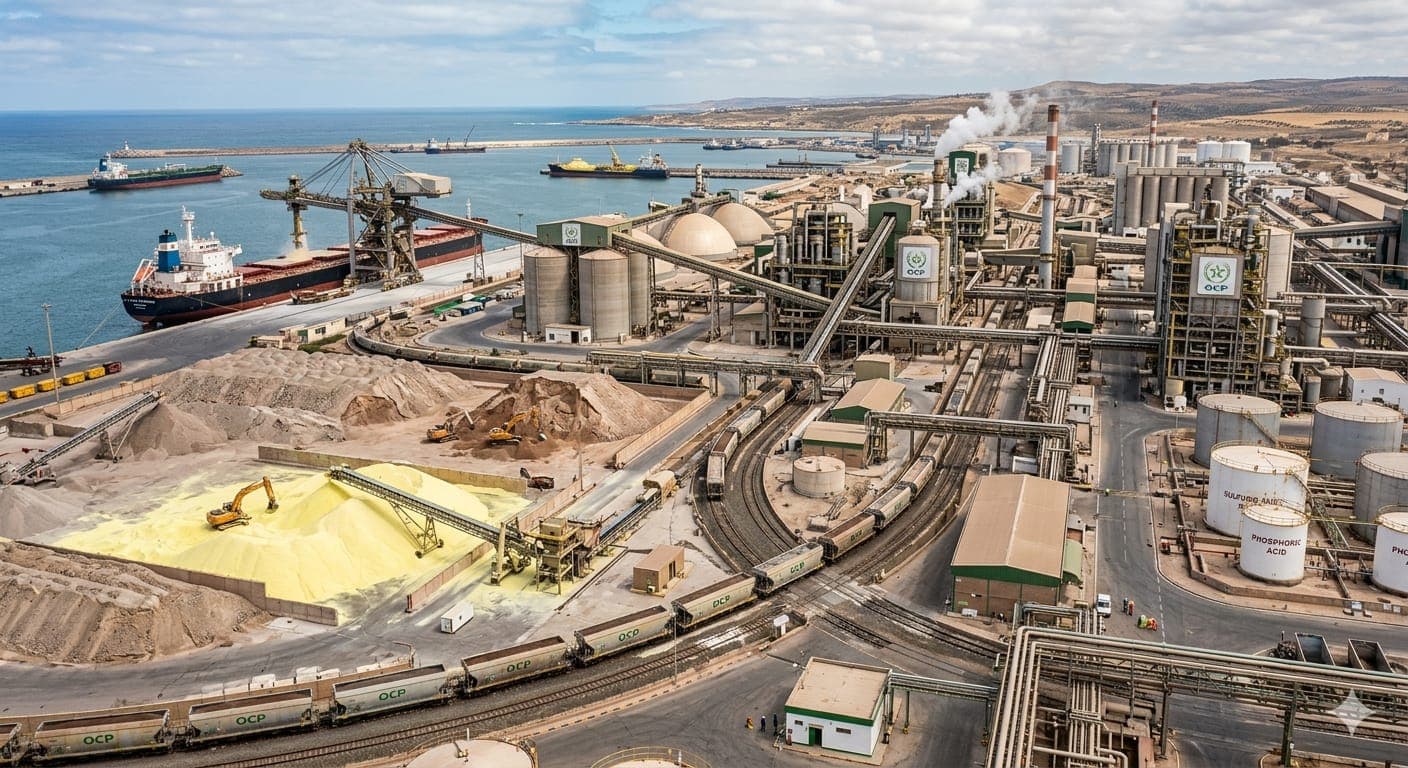
Diammonium Phosphate (Technical 18-46) - Morocco CAS: 7783-28-0
The upcoming VCI Q2 2026 report underscores a sharp decline in German chemical production, driven by soaring feedstock costs and weak domestic demand. Naphtha‑based downstream plants are hit hardest, while export disruptions to Asia and the Gulf further strain utilization rates. For buyers, the data offers critical insight into supplier stability and pricing dynamics across Europe.
China's rapid expansion of PTA and PX capacity has reshaped the global polyester supply chain entering Q3 2026. While Gulf PX supply gradually returns, Chinese overcapacity continues to pressure export prices, creating new opportunities and challenges for buyers across Asia.
The PE and PP market outlook for 2026 remains shaped by slow supply recovery, ongoing risk premiums and Gulf production constraints after Hormuz disruptions. Buyers should prepare for a longer normalization period instead of expecting immediate returns to pre-crisis pricing.
rea prices have fallen nearly 37% in a month after reaching multi-year highs during the Hormuz disruption. Procurement teams now face a market shaped by volatile supply, shifting trade flows and uncertainty over the second half of 2026.
By 2026 the sodium bicarbonate market will see a dip in industrial use driven by construction sector softness, while food‑grade demand stays flat. Europe’s supply chain faces energy‑price pressure, reshaping supplier dynamics and pricing strategies.
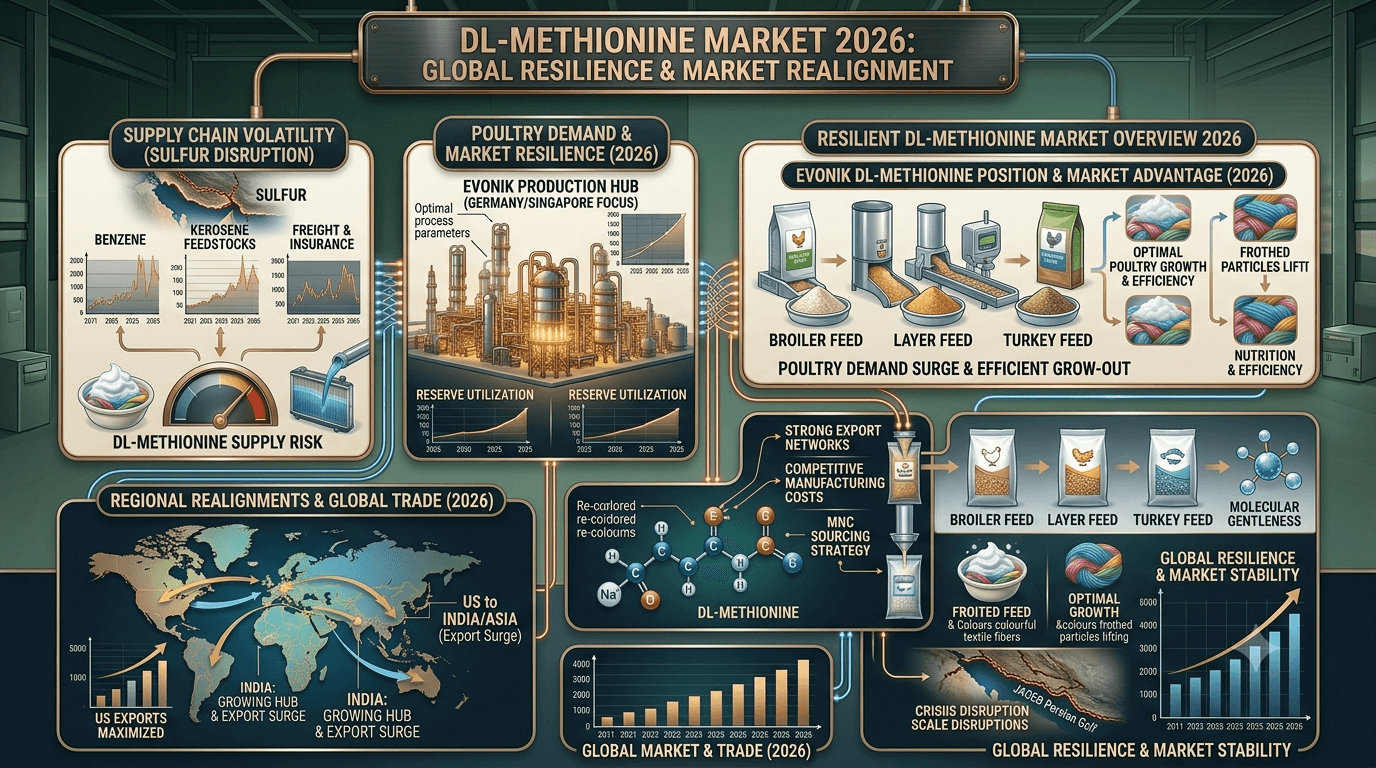
DL-methionine demand remains strong as poultry production expands globally, while sulfur supply disruptions continue to influence production costs and market dynamics.
Estamos comprometidos com sua privacidade. A Tradeasia usa as informações fornecidas para entrar em contato com você sobre conteúdos, produtos e serviços relevantes. Para mais informações, consulte nossa política de privacidade.