
Corn Gluten Feed CAS: 66071-96-3
Corn Gluten Feed CAS: 66071-96-3

Guar gum buyers face pivotal H2 2026 decisions as Rajasthan planting advances while food and oilfield demand keeps the market buoyant. This article examines crop progress, price trends, and procurement strategies for the next two quarters.
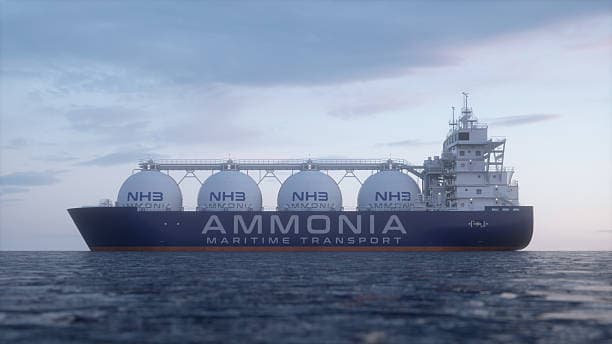
FACT India’s new 2026 ammonia tender marks a decisive move toward formula‑linked contracts, offering stability in a market plagued by volatile fertilizer prices. This long‑duration deal signals a strategic shift in fertilizer procurement, providing a predictable pricing framework for the next decade.

Thai sorbitol production is tightening as the annual tapioca feedstock gap reduces output, while Chinese suppliers continue operating at stable capacity with competitive export pricing. Procurement teams planning H2 2026 purchases have a valuable opportunity to lock in improved delivered costs before seasonal market dynamics shift again.
Brent crude has returned to pre-war levels, creating a new opportunity for food ingredient buyers to reduce landed costs. July freight adjustments give procurement teams a timely chance to renegotiate contracts across major sourcing regions including China, Southeast Asia and India.

OCP Morocco has become the dominant phosphate supplier of 2026 as Gulf fertilizer exports remain constrained. With July tender results approaching, buyers should prepare for OCP to set the global DAP pricing benchmark for Q3 contract negotiations.
Formaldehyde producers may finally see feedstock cost pressure ease as methanol supply conditions improve and crude oil prices remain softer. However, buyers of urea-formaldehyde and phenol-formaldehyde resins should not expect immediate price reductions, as contract structures and inventory cycles will delay market adjustments into August 2026.
Estamos comprometidos com sua privacidade. A Tradeasia usa as informações fornecidas para entrar em contato com você sobre conteúdos, produtos e serviços relevantes. Para mais informações, consulte nossa política de privacidade.